The New £2 Million Mansion Tax: What Property Owners Need to Know Before 2028
Own a high-value property in England? From April 2028, homeowners with properties worth £2 million or more are expected to face an additional annual property tax of up to £7,500.
The government has announced plans for a new High Value Council Tax Surcharge (HVCTS), commonly referred to as the Mansion Tax.
The charge is intended to address concerns that the existing council tax system does not adequately reflect the value of the most expensive properties.
Although the new surcharge is not scheduled to begin until April 2028, owners of potentially affected properties should understand how the proposals could influence their future finances.
What is the High Value Council Tax Surcharge?
The High Value Council Tax Surcharge is a proposed annual charge on owners of residential properties in England valued at £2 million or more.
It will be charged in addition to existing council tax, rather than replacing it.
Unlike ordinary council tax, which is generally payable by the occupier, the new surcharge is intended to be the responsibility of the property owner.
This distinction is particularly important for landlords and owners of high-value investment properties.
The government estimates that fewer than 1% of residential properties will be affected.
How much will the Mansion Tax cost?
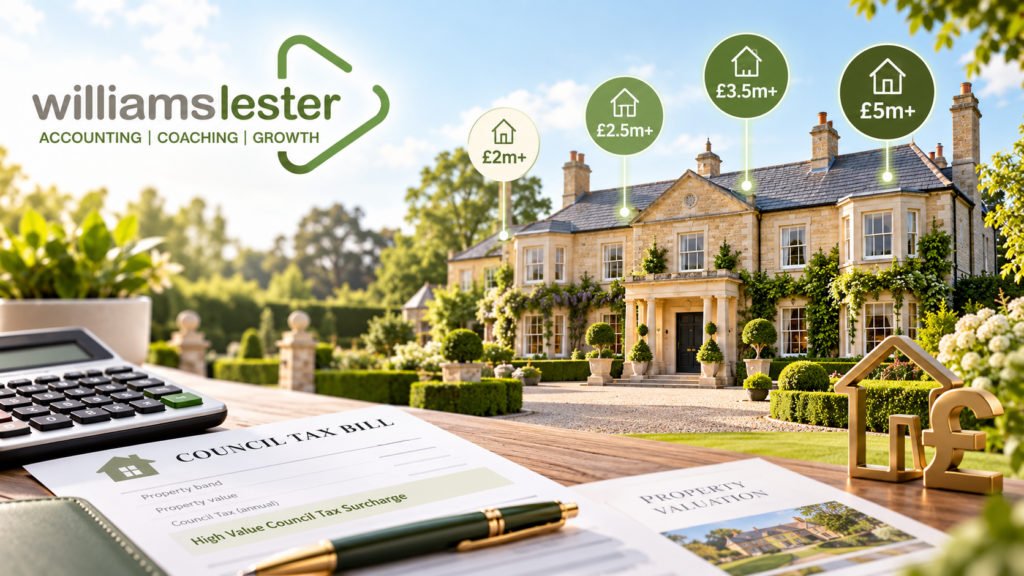
The government has announced four proposed valuation bands for the first year of operation, 2028/29.
| Property value | Annual surcharge |
| £2 million to £2.5 million | £2,500 |
| Over £2.5 million to £3.5 million | £3,500 |
| Over £3.5 million to £5 million | £5,000 |
| Over £5 million | £7,500 |
The annual charge is intended to increase in line with Consumer Prices Index (CPI) inflation from 2029/30 onwards.
These amounts are additional to the property’s normal council tax bill.
Example: Owning a £3 million property
Imagine you own a residential property in England valued at £3 million.
Under the proposed system, it would fall within the second valuation band.
You would face an additional annual surcharge of £3,500.
That is equivalent to approximately £292 per month, on top of your existing council tax.
Over five years, the surcharge would amount to at least £17,500, assuming no changes to the band or annual charge. In practice, inflation-linked increases could make the total higher.
For property owners approaching retirement or managing substantial but relatively illiquid assets, this represents an additional financial commitment worth planning for.
How will property values be determined?
The Valuation Office will undertake a targeted valuation exercise to identify properties falling within the new system.
Rather than valuing every property in England, the exercise will focus on homes potentially worth at least £2 million.
Properties will be allocated to one of the four surcharge bands.
The government proposes that revaluations should take place every five years.
The first charging period is scheduled to begin in April 2028, with a subsequent general revaluation expected in 2033.
Property owners may therefore find that changes in market values affect their future liability.
What if a property is rented out?
One significant difference between the proposed surcharge and ordinary council tax is who will be responsible for paying it.
Under the government’s proposals, the owner rather than the tenant will generally be liable.
For example, suppose you own a £4 million residential investment property that is rented to tenants.
The proposed annual surcharge would be £5,000.
That liability would fall on you as the property owner, even though the tenants occupy the property.
This makes the surcharge particularly relevant to landlords with high-value residential portfolios.
It may need to be factored into rental profitability forecasts and longer-term investment decisions.
The detailed rules for different ownership structures remain subject to the final legislation.
Will the Mansion Tax apply in Wales?
No. The announced High Value Council Tax Surcharge applies to England only.
It does not currently extend to residential properties situated in Wales, Scotland or Northern Ireland.
For example, a £3 million residential property in Cardiff would not fall within this particular proposed surcharge.
However, property owners in Wales should remember that council tax is devolved and separate Welsh rules apply.
Welsh property taxes and council tax arrangements may change independently.
This distinction is particularly important for investors holding properties on both sides of the England–Wales border.
What if you own a valuable property but have limited income?
One of the key concerns surrounding the Mansion Tax is the potential impact on people who are asset-rich but cash-poor.
Consider someone who purchased a property many years ago for a relatively modest amount.
The property may now be worth more than £2 million because of significant increases in local house prices.
However, the homeowner may be retired and living on a comparatively modest pension.
An additional annual charge of £2,500 or more could place considerable pressure on their household budget.
The government has recognised this concern and consulted on possible support measures for people who may struggle to pay.
The final details of any payment support, deferrals, discounts or exemptions have not yet been confirmed.
Can homeowners challenge their valuation?
The government intends to provide a process through which property owners can challenge their valuation band or liability.
This could be particularly relevant where a property is close to one of the surcharge thresholds.
For example, a valuation of £2.49 million would place a property in a different band from one valued at £2.51 million.
The difference could be £1,000 per year under the proposed charging structure.
Having appropriate evidence of the property’s condition, characteristics and market value may therefore become important.
What happens if the property is owned by a company or trust?
Property ownership arrangements can sometimes be more complicated than an individual owning a home directly.
High-value residential properties may be owned through companies, partnerships, trusts or other structures.
The government has consulted on how the surcharge should apply in these situations.
Owners should not assume that placing a property into a company or another structure will remove the liability.
Equally, changing ownership purely because of the proposed charge could introduce other tax consequences, including Capital Gains Tax, Stamp Duty Land Tax or other liabilities.
Any restructuring should be considered carefully and with professional advice.
Is the Mansion Tax definitely going ahead?
The government has announced its intention to introduce the High Value Council Tax Surcharge from April 2028.
However, as at October 2026, the detailed legislation has not yet been finalised.
A consultation on the design of the charge closed in July 2026.
The government has been considering issues including valuation methods, exemptions, support for homeowners, payment arrangements and appeals.
The legislation giving effect to the surcharge is expected to be introduced through a future Finance Bill.
Property owners should therefore distinguish between the announced charging structure and the detailed rules that have yet to be confirmed.
What should property owners do now?
Although implementation is still some time away, owners of potentially affected properties can begin considering the financial implications.
It may be sensible to review:
- The estimated current market value of the property.
- Whether the property is likely to exceed the £2 million threshold.
- The effect of the proposed surcharge on household budgets or rental profitability.
- Any ownership structures that might be affected.
- The potential need for independent valuation evidence.
- Future retirement, succession or estate planning decisions.
The key is to understand the potential cost before it becomes an annual liability.
How williams lester accountants can help
At williams lester accountants, we work with property investors, landlords and business owners to help them understand the financial implications of changing tax rules.
Whether you own a single high-value property or a portfolio of residential investments, we can help you assess the impact of proposed tax changes and incorporate potential liabilities into your financial plans.
We can also provide support with property investment structures, tax planning and cash-flow forecasting.
Own property in England worth £2 million or more?
Now is a sensible time to consider how the proposed surcharge might affect your financial plans.
This article reflects government announcements and consultation proposals available in October 2026. The High Value Council Tax Surcharge is proposed to commence in April 2028, subject to the necessary legislation and final detailed rules.