Borrowing Money to Withdraw Capital from Your Business?
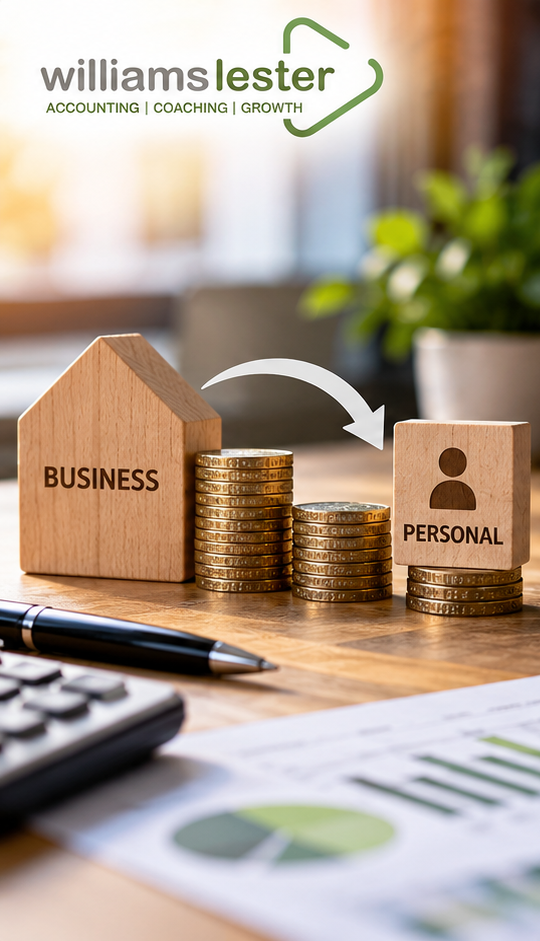
If you’ve invested your own money into your business and are considering taking some of it back, recent changes to HMRC’s guidance could have unexpected tax consequences.
For many business owners, putting personal savings into their business is simply part of getting started. As the business grows and becomes financially stronger, it is perfectly natural to want to withdraw some of that original investment.
But what happens if the business needs to borrow money to replace the funds you’ve withdrawn?
Until recently, the position on claiming tax relief for interest on that borrowing was generally more straightforward. However, changes introduced by HMRC in July 2026 have raised concerns among accountants and tax advisers.
What’s changed?
On 1 July 2026, HMRC updated sections of its Business Income Manual dealing with business borrowing and the withdrawal of capital.
The changes specifically affect sole traders, partnerships and property businesses rather than limited companies, which operate under different tax rules.
Historically, business owners could generally introduce capital into their business, withdraw that capital or accumulated profits later, and replace the funding with a business loan.
Provided the borrowing did not exceed the capital properly available for withdrawal, interest on the replacement borrowing could generally qualify for tax relief.
HMRC’s revised guidance places greater emphasis on the actual purpose of the borrowing.
The key question is now whether the borrowing was genuinely undertaken for business purposes or whether it was used to finance personal expenditure.
An example: £60,000 withdrawn from a business
Imagine Sarah runs a successful business that she originally funded using £100,000 of her personal savings.
Several years later, she decides she would like to withdraw £60,000 to help purchase a holiday property.
Rather than reduce the working capital available to her business, she arranges a £60,000 bank loan.
The loan carries an interest rate of 5%, creating an annual interest cost of £3,000.
Under the previous interpretation of HMRC’s guidance, that interest would generally have qualified as a business expense, assuming the capital account conditions were satisfied.
Under the revised guidance, HMRC may examine whether the real purpose of the new borrowing was to finance Sarah’s private purchase.
If HMRC concludes that the borrowing was for personal rather than business purposes, some or all of the interest deduction could be challenged.
For a higher-rate taxpayer, losing tax relief on £3,000 of annual interest could mean an additional £1,200 in income tax every year.
But what if the business borrowed the money originally?
This is where the revised guidance creates a particularly interesting distinction.
Suppose Sarah had originally funded her business with £40,000 of savings and a £60,000 commercial loan.
If that loan was used entirely for qualifying business purposes, the interest would ordinarily be deductible.
Compare that with introducing £100,000 personally and replacing £60,000 with borrowing several years later.
Although the business may ultimately have the same level of working capital and borrowing, HMRC could reach a different conclusion about the deductibility of the interest.
Importantly, this does not mean all replacement borrowing is automatically disallowed. The precise circumstances, the purpose of the loan and the history of the business funding remain relevant.
What about borrowing against a business property?
Property owners need to be particularly careful.
For example, a landlord might remortgage a rental property to release capital for personal expenditure.
The fact that the loan is secured against a rental property does not automatically make the interest an allowable property business expense.
HMRC will consider what the additional borrowing was actually used for and whether it meets the relevant business purpose requirements.
Similarly, borrowing to renovate a commercial property used in the business may be treated differently from borrowing secured on the same property to finance a personal purchase.
Does this mean the law has changed?
Not necessarily.
HMRC has changed its interpretation and guidance, rather than Parliament introducing new legislation specifically restricting these capital withdrawals.
The underlying legislation continues to require business expenses to satisfy the wholly and exclusively test.
HMRC’s manuals are guidance for its officers, not legislation in themselves.
Nevertheless, the revised wording suggests that HMRC may examine these arrangements more closely and potentially challenge claims that would previously have attracted less scrutiny.
What should business owners do?
If you’re considering withdrawing a substantial amount of capital from your business, there are several important steps to take:
- Review your capital account. Establish how much capital and accumulated profit is genuinely available to withdraw.
- Understand the purpose of any borrowing. Consider whether the funds are being used for business expenditure or personal purposes.
- Keep clear records. Document the original investment, subsequent drawings and use of borrowed funds.
- Consider the tax cost. Interest that does not qualify for tax relief can make borrowing significantly more expensive.
- Take advice before arranging finance. Restructuring business funding after the event may be considerably more difficult.
How williams lester accountants can help
At williams lester accountants, we believe borrowing decisions should support both your business and your personal financial goals.
Whether you’re restructuring existing finance, withdrawing capital, investing in business assets or considering a property remortgage, we can help you assess the potential tax consequences before you commit.
As accountants and business growth advisers, we look beyond the immediate transaction to understand its impact on profitability, cash flow and your longer-term plans.
Thinking about withdrawing capital or refinancing your business?
Speak to williams lester accountants before making your next move. A conversation today could help you avoid unexpected tax costs tomorrow.
This article provides general information based on HMRC guidance published in July 2026. The tax treatment of borrowing depends on individual circumstances and the applicable legislation.